Can a refund check for insurance overpayments be made payable to the estate and sent to the estate’s mailing address? – South Carolina
Short Answer
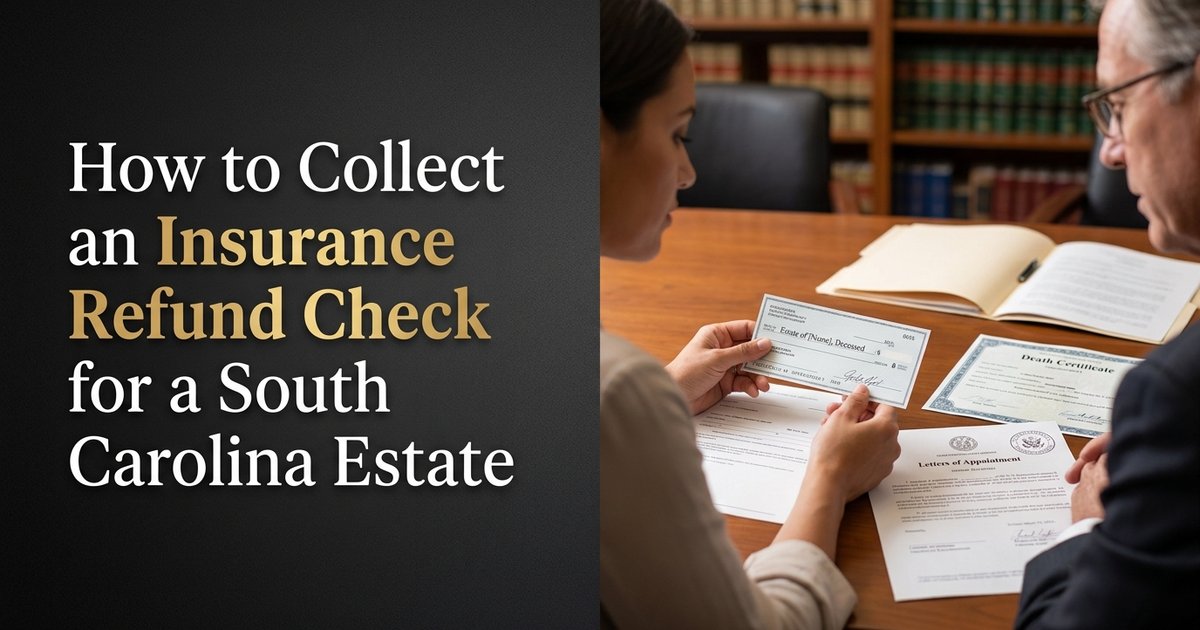
Yes. An insurer may generally make a premium-refund check payable to a South Carolina estate and mail it to an address authorized by the estate’s appointed personal representative, including counsel’s office address. The refund is not necessarily automatic; the insurer or marketplace may first require proof of death, proof of appointment, written mailing instructions, and confirmation of the coverage termination date and refund amount.
Understanding the Problem
The issue is whether a South Carolina personal representative can collect an insurance premium refund owed after a policyholder’s death by having the check issued to the estate and mailed to the estate’s designated address. The decision turns on whether the refund belongs to the estate, whether the personal representative has received authority from the Probate Court, and whether the insurer accepts the requested payee and mailing instructions.
Apply the Law
South Carolina law gives an appointed personal representative authority and responsibility to take control of estate property. A right to recover premiums paid from the decedent’s or estate’s funds will generally be treated as an estate asset unless the insurance contract, the source of the payments, or another controlling rule gives the refund to someone else. For a decedent domiciled in South Carolina, the Probate Court for the county where the decedent was domiciled appoints the personal representative and issues the documents showing that authority; for a nonresident decedent, venue may be in a county where the decedent’s property was located.
Key Requirements
- Estate ownership: The refunded premiums must belong to the decedent or estate. If another person paid the premiums from personal funds, ownership may require additional review.
- Authority to collect: The person requesting payment should be the court-appointed personal representative or an authorized representative acting under that person’s direction.
- Acceptable payee: The insurer may issue the check to “Estate of the deceased policyholder” or to the personal representative in that representative capacity. The insurer and the estate’s bank may require specific wording.
- Verified mailing instructions: Mailing the check to counsel’s office does not change ownership of the funds, but the personal representative should authorize that address in writing and comply with the insurer’s verification procedures.
- Proper administration: The personal representative should deposit the refund into the estate account, preserve supporting records, and report the receipt as required during the probate administration.
What the Statutes Say
- S.C. Code Ann. § 62-3-103 (Appointment and Letters) – A person generally must be appointed, qualify, and receive letters before exercising a personal representative’s powers.
- S.C. Code Ann. § 62-3-709 (Possession and Control of Estate Property) – The personal representative must take control of estate property and protect it during administration.
- S.C. Code Ann. § 62-3-706 (Inventory and Appraisement) – The personal representative generally must file an inventory of probate property owned at death within 90 days after appointment.
- S.C. Code Ann. § 62-3-708 (Supplementary Inventory) – Property omitted from an original inventory may require a supplementary, amended, or corrected inventory.
Analysis
Apply the Rule to the Facts: The requested refund concerns premiums paid after the policyholder’s death, so the insurer must first determine whether coverage should end retroactively and whether an overpayment exists. If the premiums came from the decedent’s or estate’s funds, the appointed personal representative may request a check payable to the estate. The personal representative may also direct delivery to counsel’s office, but the insurer can require written authorization and supporting probate documents.
South Carolina probate law supports the personal representative’s collection of an estate asset, but it does not require an insurer to issue the refund automatically or use a particular mailing address. Backdating coverage and calculating the refund remain administrative matters for the marketplace and insurer. Once received, the check should not be deposited into a beneficiary’s, family member’s, or law office operating account; it should ordinarily go into the estate account.
Process & Timing
- Who files: The appointed personal representative, directly or through authorized counsel. Where: The refund request goes to the insurer or marketplace, while proof of appointment comes from the Probate Court with proper venue, generally in the county where a South Carolina decedent was domiciled or, for a nonresident decedent, a county where the decedent’s property was located. What: A written request should include the death certificate, current letters of appointment, policy information, requested termination date, requested payee wording, and authorized mailing address. When: South Carolina probate law does not impose one universal deadline for insurance premium refunds, so any insurer or marketplace deadline should control.
- The insurer or marketplace reviews the termination date, payment history, source of the premiums, and authority of the requester. Processing time varies, and the personal representative should obtain written confirmation rather than assume that the refund will issue automatically.
- After approval, the insurer issues the check using its accepted payee format. The personal representative deposits it into the estate account, keeps the remittance statement and correspondence, and records the receipt for probate reporting. If a check arrives in the deceased person’s name alone, the estate may need to request reissuance; additional guidance appears in this article about reissuing an insurance refund check to a South Carolina estate.
Exceptions & Pitfalls
- Someone else paid the premiums: A refund may belong to the actual payor rather than the estate, depending on the payment source and governing contract terms.
- No appointed personal representative: A will nomination or family relationship alone does not establish authority. The Probate Court generally must appoint the personal representative and issue letters.
- Incorrect payee wording: A bank may reject a check payable only to the deceased policyholder or may require wording that identifies the personal representative’s capacity.
- Address confusion: An insurer may refuse to mail the check to counsel until it receives written authorization. The request should clearly distinguish the mailing address from the check’s payee.
- Assuming the refund is automatic: Reporting the death does not necessarily trigger payment. The estate should request written confirmation of termination, the effective date, the refund calculation, and the expected payment method.
- Closed estate: If the refund appears after the estate has closed and the personal representative has been discharged, an interested person may need to ask the Probate Court to reopen the administration under S.C. Code Ann. § 62-3-1008.
Conclusion
An insurance overpayment refund may generally be made payable to a South Carolina estate and mailed to an address authorized by the appointed personal representative. The insurer may require letters of appointment, proof of death, payment records, and written mailing instructions, and no rule makes the refund automatic. Have the personal representative submit one complete written request to the insurer or marketplace promptly and before any claim or reissuance deadline stated in its procedures.
Talk to a Probate Attorney
If an estate is seeking an insurance premium refund after a policyholder’s death, our firm has experienced attorneys who can help document the personal representative’s authority, request proper payee wording, and address probate reporting requirements.
Disclaimer: This article provides general information about South Carolina law based on the single question stated above. It is not legal advice for your specific situation and does not create an attorney-client relationship. Laws, procedures, and local practice can change and may vary by county. If you have a deadline, act promptly and speak with a licensed South Carolina attorney.